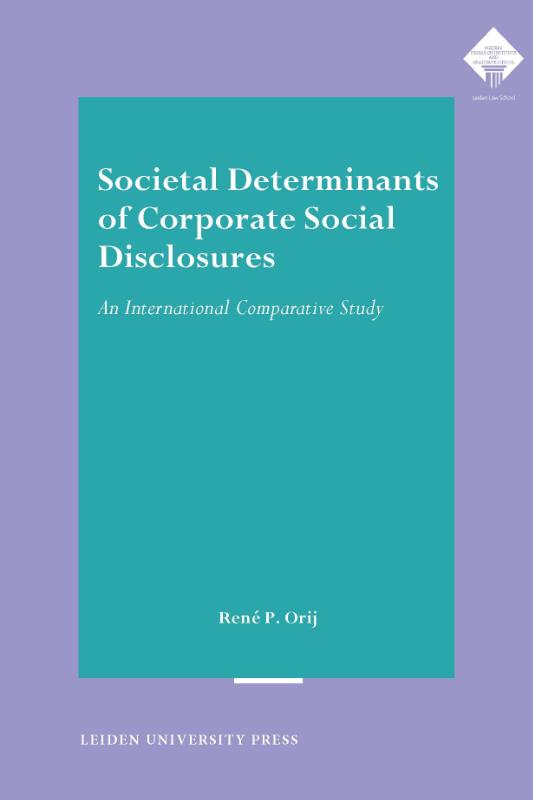
Societal determinants of corporate social disclosures an international comparative study
Corporations disclose social information which is likely to relate to their social responsibility activities. The disclosed social information is called social disclosures, a term borrowed from financial accounting and reporting. Why do corporations want to disclose information regarding their social responsibility activities? This study contains a search for the answer to that question. It is a study on the societal determinants of corporate social disclosures. The considered societal determinants are institutional and they are explained by a system-theoretical framework of stakeholder and legitimacy theory.
According to the currently dominant research paradigm in financial accounting, corporations have a narrow focus on the decision-usefulness of corporate information and the creation of shareholder value. This study is different. It assumes that managers are aware of the bigger picture of society and the position of their corporations in society. In this study it is shown that managers can have a broader focus than just on shareholder value creation.
This is a volume in the series of the Meijers Research Institute and Graduate
School of Leiden University.
In het kort
ISBN-13
9789087281625
Verschenen
27 maart 2012
Serie
Imprint
Bibliografisch
Uitgave
Vorm & inhoud
ProductvormPaperback BC
SamenstellingLos product
Classificatie
NUR (hoofd)Internationale financiële economie 784
NUR (alle)784 Internationale financiële economie
Medewerkers
Auteur A01René Orij
Herkomst
Werk-id (NSTC)500513316
MeldingBevestigd bij publicatie 03
Bijgewerkt6 augustus 2026
Lijkt op dit boek
NSTC 500513316 · CB-relatie 6345163 · Bijgewerkt 6 augustus 2026